
The T+1 Arrival: Is Your Firm Built for Speed?

Executive Summary
The global capital markets are undergoing one of the most fundamental structural transformations in decades: The migration from a T+2 (trade date plus two business days) settlement cycle to T+1 (trade date plus one business day). Following the successful implementation of T+1 across major North American and international jurisdictions, global financial markets have established a new baseline for operational velocity, liquidity management, and risk mitigation.
For South African market participants, financial advisors, and wealth managers, this global acceleration is no longer a distant macroeconomic topic; it is a pressing operational reality. As market infrastructure providers, central securities depositories (CSDs), broker-dealers, and regulators evaluate and prepare for South Africa’s transition toward accelerated settlement, market participants must ask a critical strategic question: Is your firm built for speed?
This technical Continuous Professional Development (CPD) article explores the core drivers of the T+1 settlement revolution, the structural and operational impacts on investment portfolios and client management, and the high-level readiness framework required for financial planning practices and asset management firms.
Section 1: Contextualising the Global Shift to T+1
1.1 The Evolution of Settlement Cycles
For decades, capital market infrastructure operated on extended time horizons between trade execution and final settlement. In the era of physical stock certificates, paper ledger entries, and manual clearance protocols, settlement cycles of T+5 (trade date plus five business days) or even T+7 were standard across global exchanges. These multi-day buffers were essential operational allowances, permitting broker-dealers, clearinghouses, transfer agents, and custodian banks to physically verify ownership certificates, transfer paper documents across institutions, and manually reconcile balance sheets.
As financial markets transformed through electronic trading platforms, central depository systems, and automated messaging standards, such as SWIFT networks, the physical necessity for prolonged settlement windows largely dissolved. The market evolved from T+5 to T+3 in the late 1990s, and subsequently from T+3 to T+2 across major global markets between 2014 and 2017. However, even under a T+2 framework, the fundamental structural mechanism remained unchanged: Trade execution (T) and final settlement (S) remained asynchronous events separated by a two-day operational gap.
The primary structural driver behind compressing the settlement cycle to T+1 (trade date plus one business day) is the systematic reduction of risk across the post-trade lifecycle. The period between trade execution and final settlement represents a window of latent financial exposure. During this interval, market participants are exposed to three primary forms of risk:
- Counterparty Default Risk: The risk that either the buyer or seller defaults on their obligation prior to the transfer of securities or cash. In periods of extreme market volatility or institutional distress, a two-day settlement window leaves clearinghouses and non-defaulting counterparties vulnerable to contagion.
- Market Risk: The risk that the price of the underlying security moves drastically against one of the counterparties during the unsettled period. The greater the time elapsed between price lock-in and final exchange of value, the higher the potential loss if a party fails to fulfil their obligations.
- Credit and Liquidity Risk: To insulate the ecosystem against counterparty default and market volatility during the T+2 window, central clearinghouses require clearing members to post substantial collateral in the form of initial margin and variation margin. This capital remains locked up for two days, incurring opportunity costs and constraining market liquidity.
Mathematically, the relationship between settlement duration and capital exposure is direct. By compressing the settlement window from two days to one day, the volume of open, unsettled transactions present in the market system at any given moment is reduced by approximately 50%.
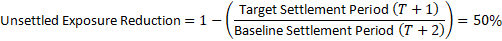
This 50% drop in systemic open exposure translates into lower initial margin requirements for market participants. The freeing up of margin collateral releases significant capital back into active treasury management and market-making activities, lowering overall systemic friction, reducing capital costs, and increasing total market efficiency.
1.2 Global Precedents and Cross-Border Interoperability
The global transition to T+1 gained unstoppable momentum when major capital markets implemented accelerated settlement regimes. North America led this systemic shift, with the United States, Canada, and Mexico successfully transitioning equity, corporate bond, and municipal security settlement to T+1 in May 2024. Prior to this, India completed a phased transition to T+1 for all listed equities by early 2023, while mainland China operated on a T+0 or T+1 model for selected asset classes.
The migration of the world’s largest equity market, the United States, to T+1 created a structural ripple effect across the global financial architecture. As global capital flows are deeply interconnected through cross-border portfolio investments, dual-listed securities, global depository receipts (GDRs), exchange-traded funds (ETFs), and multi-currency derivatives, a shift in US market velocity instantly recalibrated operational requirements for international market participants, including those in South Africa.
For South African institutional investors, asset managers, wealth planners, and banking custodians operating within an environment where domestic markets still settle on a T+2 basis while key international counterparts settle on T+1, a major challenge emerges: Cross-border operational friction and funding asymmetry.
| CROSS-BORDER T+1 vs T+2 ASYMMETRY |
| Leg 1: Selling US Equity (Settles in 1 Business Day – T+1) → Cash received on T+1 in USD. |
| Leg 2: Reinvesting in Domestic SA Equity (Settles in 2 Business Days – T+2) → Cash required on T+2 in ZAR. |
| Operational Challenge: Currency Conversion & Same-Day Cut-Offs → Executing USD/ZAR FX conversions within compressed timeframes to avoid cash drag, overdraft fees, or settlement mismatches. |
This structural asymmetry manifests across several core areas:
1. Time-Zone Compression and Post-Trade Cut-offs
Operating from South Africa (SAST / UTC+2) to execute transactions in North American markets (T+1) imposes extreme time-zone compression. Under T+2, post-trade allocation, trade confirmation, and instruction matching could comfortably extend into the morning of T+1. Under T+1, post-trade processing windows are slashed from roughly 12 to 15 hours down to a narrow window of just 2 to 4 hours on trade date (T).
2. Foreign Exchange (FX) Execution and Liquidity
Executing cross-border portfolio rebalancing requires simultaneous settlement of securities and the underlying foreign exchange contract. When purchasing a US security from South Africa under T+1 , the cash proceeds must be funded and converted within a 24-hour cycle. If FX instruction cut-offs, such as those dictated by Continuous Linked Settlement (CLS) bank deadlines, pass before trade allocations are matched, institutional investors are forced to either pre-fund FX accounts or utilise costly short-term credit facilities to bridge the liquidity gap.
3. ETF and Multi-Asset Class Mismatches
A significant volume of modern financial planning relies on Exchange-Traded Funds (ETFs) and global collective investment schemes. When an underlying ETF holds global basket components settling on varying schedules (e.g., US equities settling on T+1 alongside European or emerging market equities settling on T+2), primary market basket creation and redemption mechanics experience tracking errors, pricing latency, and increased creation-unit borrowing costs.
As European, UK, and other global jurisdictions continue preparing for their own official transitions toward accelerated settlement, international market consensus is clear: T+1 is no longer an optional innovation; it is the emerging global standard for capital market infrastructure. South African firms that structure their operational models around legacy T+2 timelines face growing cross-border friction, higher transaction costs, and elevated risk profiles when engaging with international investment flows.
Section 2: The South African Landscape: The Road to Accelerated Settlement
2.1 The Domestic Ecosystem
South Africa’s capital markets infrastructure is widely recognised as one of the most sophisticated, resilient, and highly regulated in emerging markets. The domestic post-trade landscape is anchored by a tightly integrated tri-party structure: the Johannesburg Stock Exchange (JSE) as the primary market operator and front-end trading engine, Strate as the licensed Central Securities Depository (CSD), and the South African Reserve Bank (SARB) managing ultimate cash leg finality via the South African Multiple Option Settlement (SAMOS) system.
Historically, South Africa has successfully navigated settlement compression cycles. The domestic equity market migrated from paper-based T+5 clearance to electronic T+3 rolling settlement in the early 2000s, followed by a landmark transition from T+3 to T+2 in 2016. This track record demonstrates that South African financial market infrastructure (FMI) possesses robust straight-through processing (STP) foundations, centralised electronic register keeping, and proven architectural flexibility.
| SOUTH AFRICAN DOMESTIC POST-TRADE VALUE CHAIN |
| Trade Execution → JSE Equity Trading Engine (Matching & Execution) |
| Trade Allocation → Asset Managers, DFMs & Wealth Management Platforms |
| Clearing & CSD → Strate (Central Securities Depository – Securities Leg) |
| Cash Finality → SARB SAMOS System (Real-time Gross Settlement – Cash Leg) |
However, migrating the South African ecosystem to a T+1 standard involves far more than an operational adjustment at the exchange or CSD level. In a T+1 environment, post-trade activities must compress into a narrow window on trade date (T). Key institutional components across the domestic value chain face unique operational hurdles:
- Asset Managers & Discretionary Fund Managers (DFMs): Must finalise fund allocations, trade confirmations, and sub-account instructions within hours of market close, leaving negligible room for manual trade reconciliation or Excel-based instruction generation.
- Management Companies (Mancos) & LISP Platforms: Linked Investment Service Providers (LISPs) and unit trust Manco administrators must synchronise pricing valuation points (NAV calculations), unit creation or redemption instructions, and cash transfers to align with accelerated stockbroking settlement.
- Custodian Banks & Primary Clearing Members: Must execute real-time instruction matching in Strate and guarantee cash funding in SAMOS earlier in the operational window to avoid steep late-reporting or fail penalties.
- Foreign Exchange Operators & SARB Regulations: Domestic market participants operating under exchange control guidelines must manage cross-border capital inflows and outflows through authorised dealers with unprecedented speed to match same-day or early T+1 security clearing cut-offs.
2.2 Why T+1 Matters for Advisory and Wealth Practices
For many independent financial advisors (IFAs), wealth management practitioners, and compliance officers, settlement cycles have historically been perceived as technical back-office clearing mechanics handled invisibly by stockbrokers, platforms, and custodians. In a modernised wealth management practice, however, settlement velocity directly influences client experience, portfolio execution efficiency, and practice operational risk.
Accelerated settlement alters the operational interface between financial planners, platforms, and clients across four vital operational areas:
1. Portfolio Rebalancing and Model Portfolio Execution
Wealth management practices frequently utilize discretionary model portfolios managed internally or via DFMs. Rebalancing a multi-asset model portfolio typically requires a sequence of interdependent transactions: liquidating offshore or domestic equities, waiting for cash settlement, executing foreign exchange conversions, and buying target asset classes.
Under T+2, this multi-leg chain often creates multi-day cash drag, where uninvested capital sits idle, exposing the client to market movement risk (opportunity loss) during volatile market phases. Under T+1, capital moves through the execution chain at double the speed, enabling wealth managers to complete complex portfolio realignments faster, reduce uninvested cash drag, and lock in model target allocations with greater precision.
| MODEL PORTFOLIO REBALANCING COMPARISON |
| LEGACY T+2 TIMELINE: Day T: Sell Execution → Day T+2: Cash Settles → Day T+3: FX/Reinvest Buy Total Exposure Window: 3 to 4 Business Days of Cash Drag |
| ACCELERATED T+1 TIMELINE: Day T: Sell Execution –> Day T+1: Cash Settles & Reinvest Buy Executed Total Exposure Window: 1 to 2 Business Days of Cash Drag |
2. Client Withdrawals, Living Annuity Drawdowns, and Estate Distributions
Client relationships are tested during liquidity events, such as lump-sum capital withdrawals, monthly living annuity income payouts, or estate distribution liquidations following a client’s death. In legacy operational setups, platform cash payout delays are often caused by underlying T+2 settlement lags plus manual processing queues.
A move to T+1 significantly speeds up the delivery of capital to end-clients, allowing advisory firms to offer superior liquidity servicing and responsive cash management.
3. Verification of Trade Affirmations and Client Authorisations
The compressed T+1 processing window leaves virtually no leeway for delayed trade authorisations. If an advisory practice requires wet-ink signatures, manual email confirmations, or physical authorisation forms from clients prior to executing a portfolio switch or rebalance allocation, the trade risks missing intraday broker and platform cut-offs.
Practices that fail to digitise client onboarding, digital signatures, and automated instruction workflows will find themselves unable to meet the operational velocity required by platform providers in a T+1 market.
4. Operational Risk and Penalty Mitigation
Under Strate and JSE settlement rules, failed trades or late-matched allocations incur strict financial penalties and administrative surcharges. If an advisory firm or DFM submits erroneous sub-account allocations late on trade date (T), broker-dealers may be forced to hold unsettled positions in proprietary error accounts or face CSD fines.
Establishing internal operational controls that align with T+1 requirements is, therefore, essential to protect advisory practices from operational liability and reputational damage.
Section 3: Core Technical & Operational Frameworks of T+1
Achieving an accelerated T+1 settlement cycle requires a comprehensive re-engineering of post-trade operational mechanics. When the execution-to-settlement timeline is compressed by 50%, legacy friction points, manual interventions, and operational latencies that were easily absorbed under T+2 immediately transform into severe systemic failure points. For financial planning practices, wealth management firms, and asset managers, evaluating technical readiness requires a granular understanding of three core post-trade operational frameworks: execution allocation timelines, foreign exchange (FX) management, and corporate action processing.
| POST-TRADE TIMELINE COMPRESSION: T+2 VS T+1 |
| LEGACY T+2 POST-TRADE TIMELINE: Trade Execution (T) → Allocations & Confirmations (T+1) → Pre-Settlement Matching & Cash Funding (T+2 Morning) → Final CSD Settlement & Title Transfer (T+2 Evening) |
| ACCELERATED T+1 POST-TRADE TIMELINE: Execution + Allocation + Affirmation (Trade Date T Evening) CSD Matching & Cash Funding (T+1 Morning) Final Settlement & Title Transfer (T+1 Cut-off) |
3.1 Post-Trade Execution and Allocation Timelines
Under a T+2 regime, market participants benefit from a generous post-trade window. Block trades executed by institutional asset managers or discretionary fund managers (DFMs) on Trade Date (T) can be allocated across underlying client sub-accounts well into the morning or afternoon of T+1. Stockbrokers and custodian banks then have until the evening of T+1 or early morning of T+2 to perform pre-settlement matching, verify cash and security availability, and commit instructions to the Central Securities Depository (CSD).
In a T+1 environment, this multi-day operational buffer disappears entirely. Post-trade activities must shift dramatically to the evening of Trade Date (T):
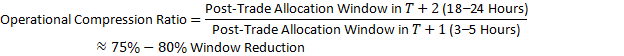
To prevent settlement failures under this compressed model, firms must implement Straight-Through Processing (STP) and automated Trade Affirmation:
- Intraday Block Allocation: DFMs and portfolio managers must submit client-level allocation files to executing brokers immediately following trade execution, rather than batching allocations at the end of the trading day.
- Automated Allocation Matching: Manual spreadsheet uploads, email instructions, and physical authorisation forms must be replaced with electronic messaging protocols (such as SWIFT or FIX protocol integrations) between investment management systems (IMS) and broker-dealer back offices.
- Same-Day Affirmation (SDA): Custodian banks and institutional clients must affirm matched trade details on
before nocturnal clearing processing begins. If trade parameters (price, volume, account number, or settlement location) mismatch, exception management workflows must identify and resolve the discrepancy in real time before the evening market cut-off.
Firms that rely on manual exception clearing under T+1 face exponential increases in failed trades, incurring significant CSD penalty fees and potential buy-in obligations.
3.2 FX Management and Cross-Border Funding
For South African wealth managers and financial advisors constructing global multi-asset portfolios, the foreign exchange (FX) management framework under T+1 presents complex operational challenges.
When a domestic client rebalances a portfolio by selling offshore equities (e.g., US-listed equities settling on T+1) to purchase domestic JSE-listed instruments, or vice versa, the transaction involves two distinct settlement legs: a securities leg governed by exchange settlement rules and a cash/currency leg governed by international banking networks (such as Continuous Linked Settlement – CLS) and local exchange control regulations.
.
CROSS-BORDER FX & LIQUIDITY FRICTION IN T+1
Step 1: Execute Global Equity Sale on T (US Market)
Step 2: Security Settles on T+1 in USD –> Cash Available on T+1
Step 3: Initiate USD/ZAR FX Conversion (Must meet CLS / Authorised Dealer Cut-off)|
Step 4: SARB/Exchange Control Verification & ZAR Funds Clearing
Challenge: Risk of Missing Same-Day Cut-off → Liquidity Gap or Overdraft
Key operational vulnerabilities in FX processing include:
- Time-Zone and CLS Cut-off Mismatches: The primary global multi-currency settlement system, CLS, enforces strict daily execution windows for same-day funding. South African asset managers executing US security trades late in the South African afternoon have a narrow window to execute the underlying USD/ZAR spot FX trade, process local Authorised Dealer approvals, and ensure funds reach the custodian account in time for T+1 security clearing.
- Liquidity and Pre-Funding Requirements: If an FX transaction fails to settle on T+1 due to cut-off delays or exchange control queries, the local buyer faces a funding shortfall on the security purchase leg. To bridge this gap, custodian banks may require asset managers to pre-fund currency accounts or maintain overdraft credit facilities, introducing unwanted interest charges and cash drag onto client portfolios.
- Automated FX Execution: To maintain T+1 alignment, advisory platforms and asset managers must transition from manual voice/email FX dealing to automated, algorithmic FX execution tools integrated directly into post-trade allocation engines.
3.3 Corporate Actions and Income Distributions
Accelerated settlement cycles fundamentally reconfigure the mechanical schedule for mandatory and voluntary corporate actions, including dividend payments, rights issues, share splits, and spin-offs.
In a legacy T+2 environment, the operational gap between the Ex-Dividend Date (Ex-Date), which is the date on which a security begins trading without its upcoming dividend entitlement, and the Record Date, or the date on which an investor must officially appear on the CSD register to receive the dividend, is typically one business day (T+2 settlement allows a buyer purchasing on Ex-1 to be registered by Record Date).
Under a T+1 framework, this structural dynamic changes:
- Ex-Date/Record Date Alignment: Because trades settle in a single business day, the Ex-Dividend Date and the Record Date typically coincide on the same day (Ex Date = Record Date).
- Impact on Income-Focused Portfolios: Financial planners managing living annuity drawdowns or income-dependent portfolios must recalibrate client distribution schedules. With Ex and Record dates merging, trade dates for dividend entitlement checks become tighter. Portfolio rebalancing executed immediately prior to corporate action cut-offs must be confirmed flawlessly to ensure clients do not inadvertently lose dividend rights during transition periods.
- Voluntary Corporate Actions Choice Windows: For complex corporate actions requiring client instructions (e.g., scrip dividend choices or rights issue subscriptions), the election window available to wealth managers and end-investors is compressed. Custodians must transmit corporate action notices and collect digital responses from advisors with unprecedented speed to aggregate and submit instructions to Strate before the shortened market deadline.
Section 4: Strategic Readiness: High-Level Evaluation for Financial Practices
Preparing an advisory practice, wealth management firm, or asset management business for an accelerated In a legacy environment, the operational gap between the Ex-Dividend Date (Ex-Date), which is the date on which a security begins trading without its upcoming dividend entitlement, and the Record Date, or the date on which an investor must officially appear on the CSD register to receive the dividend, is typically one business day (
settlement allows a buyer purchasing on
to be registered by Record Date).
Under a framework, this structural dynamic changes: T+1 settlement environment requires moving beyond basic compliance checklists. Firms must undertake a holistic structural review of their operational architecture, technology infrastructure, and counterparty relationships.
To determine whether your firm is truly built for speed, leadership teams should evaluate their operational capabilities across four core pillars:
| THE 4 PILLARS OF T+1 STRATEGIC READINESS |
| PILLAR 1: Technology & Automation Architecture Real-time API integrations, STP processing, and real-time exception management. |
| PILLAR 2: Liquidity & Working Capital Optimization Pre-funding protocols, short-term overdraft facilities, and cash drag reduction. |
| PILLAR 3: Operational Workflows & Human Capital Extended coverage shifts, digitized client signatures, and updated SOPs. |
| PILLAR 4: Risk Management & Governance Fail-fee allocation, SLA vendor audits, and regulatory reporting readiness. |
Pillar 1: Technology & Automation Architecture
The cornerstone of T+1 operational readiness is the elimination of manual touchpoints across the trade lifecycle.
- Real-Time API Integration: Does your practice management software, portfolio administration system, or CRM connect directly to LISP platforms and custodian brokers via real-time Application Programming Interfaces (APIs), or does your team rely on manual CSV file uploads and overnight batch processing?
- Straight-Through Processing (STP): Are client trade instructions, rebalance orders, and allocation files validated and transmitted automatically upon approval, or do they sit in manual review queues?
- Real-Time Exception Dashboards: When a trade allocation or account mismatch occurs, does your system generate an immediate intraday alert for operational intervention, or is the failure discovered the following morning during post-trade reconciliation?
Pillar 2: Liquidity and Working Capital Optimization
In a T+1 environment, settlement velocity compresses liquidity management windows.
- Pre-Funding Management: Does your firm have clear guidelines on pre-funding client accounts for buy orders when cross-border or inter-platform transfers face timing mismatches?
- Credit & Overdraft Facilities: Have custodian banks and broking partners established standby liquidity facilities to bridge potential FX or settlement timing gaps without triggering default penalties?
- Minimising Client Cash Drag: How efficiently does your platform mechanism sweep uninvested cash, ensuring clients do not forfeit interest income or suffer equity market tracking errors during multi-leg rebalances?
Pillar 3: Operational Workflows & Human Capital
Compressed processing windows require recalibrating internal human capital workflows and client communication protocols.
- Operating Hours & Shift Alignment: Does your operational team offer coverage into late afternoon trade-affirmation windows, particularly when managing portfolios with North American or European market exposure?
- Digital Client Experience: Have paper-based authorisation forms, physical wet signatures, and manual email confirmations been entirely replaced with secure, authenticated digital signature workflows and client portal approvals?
Pillar 4: Risk Management & Governance
Accelerated settlement alters the operational risk profile and legal framework of client mandates.
- SLA & Vendor Audits: Have you conducted a formal audit of your primary LISP platforms, custodian brokers, DFMs, and software vendors to ensure their systems are certified for T+1 velocity?
- Fail Penalty Protocols: Does your discretionary client mandate or mandate agreement clearly outline risk disclosures and liability allocation in the event of third-party market settlement fails?
Section 5: Bridging Theory and Practice
The global compression of capital market settlement cycles to T+1 represents far more than an incremental back-office infrastructure upgrade. It marks a fundamental shift in the velocity of modern finance. As international markets solidify T+1 as the global baseline, the South African financial ecosystem stands at a critical operational junction. For wealth management firms, financial advisors, and discretionary asset managers, treating accelerated settlement as a distant regulatory topic is no longer a viable strategy.
In an environment where market execution occurs in seconds, operating post-trade processes on legacy multi-day horizons introduces unnecessary structural friction, elevated counterparty risk, and portfolio cash drag. Wealth management practices that proactively modernise their operations stand to gain a clear competitive advantage:
- Superior Portfolio Agility: Multi-asset rebalancing and model portfolio switches execute with minimal time out of the market, locking in client asset allocations while reducing capital drag.
- Enhanced Client Outcomes: Liquidity events, from living annuity drawdowns to estate distributions, are fulfilled with unprecedented speed, elevating the client experience.
- Operational Resilience: Replacing fragmented, spreadsheet-driven processes with automated Straight-Through Processing (STP) insulates the practice against costly trade fails, administrative penalties, and operational errors.
Conversely, firms that delay their operational transition risk encountering severe bottlenecks: cross-border FX mismatches, funding friction, platform lock-outs, and heightened trade-failure penalties. Building a firm that is “built for speed” requires immediate, decisive action including upgrading technology architecture, establishing digitised client workflows, auditing platform partners, and fostering a culture of operational precision.
The T+1 horizon is here. The infrastructure is accelerating, and the market will not wait for slow movers. The definitive question for every South African financial practice is no longer when the market will change, but whether your operational foundation is engineered to thrive in an accelerated world.
For more information on this key topic, watch our informative podcast below.


Responses